Beyond the Boom: Analyzing Australia's Real Estate Shift in 2026
Following a period of aggressive post-pandemic growth that pushed property values to multi-decade highs, the Australian real estate market has officially entered a transformative phase. Recently, the market has visibly cooled, characterized by softening prices in major metropolitan hubs like Sydney and Melbourne, a decline in auction clearance rates, and diverging trends in mid-sized cities. This shift is not merely a cyclical adjustment of supply and demand; it is being driven by a confluence of profound policy reforms, persistently high interest rates set by the Reserve Bank of Australia (RBA), and stringent new anti-money laundering regulations. As the economic landscape evolves, a critical question emerges: is this correction a genuine window of opportunity for first-time buyers, or simply a brief pause before another cycle of escalating prices?
A Tale of Diverging Markets: Metropolis vs. Mid-Sized Cities
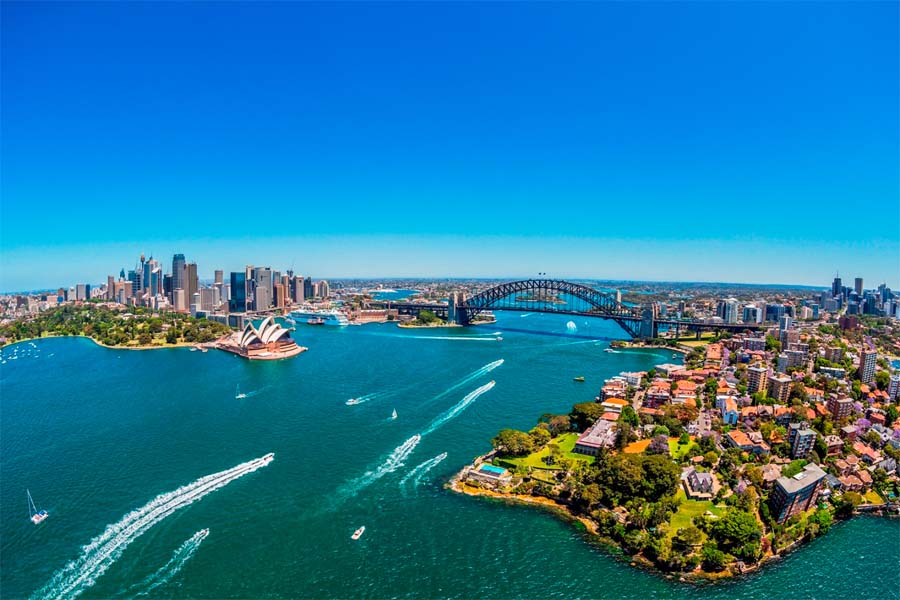
The post-pandemic property boom has definitively fractured into a multi-speed market. In major capital cities, the downward trajectory is evident. By the second quarter of 2026, housing prices in Sydney experienced an approximate decline of 3.2%, while Melbourne recorded a drop of 2.6%. Many economists project that this downward adjustment may continue over the coming months before reaching a stabilization point. The primary catalyst for this metropolitan cooling is the prolonged duration of elevated interest rates, which has severely constrained borrowing capacities and rendered peak prices fundamentally unsustainable for the average household. Despite this correction, broader financial distress remains largely absent, with mortgage arrears maintaining historically low levels.
Conversely, mid-sized markets such as Perth, Brisbane, and Adelaide continue to exhibit growth, albeit at a moderated pace compared to previous quarters. When looking at cumulative growth over recent years, Perth has recorded an impressive 30% surge, while Brisbane has seen a 20% increase. However, forecasts suggest this momentum is peaking and annual growth will stabilize to a more sustainable 5% to 8% range in upcoming periods. This persistent upward trajectory is largely fueled by relative affordability and robust interstate migration, as buyers actively seek value outside the most expensive capitals.
The Economic Ripple Effect and the Psychology of Pricing
Housing in Australia extends far beyond mere shelter; it is deeply entrenched in the broader national economy. Historically, a buoyant property market creates a "wealth effect," wherein homeowners feel financially secure, thereby stimulating discretionary spending. Research from the Reserve Bank of Australia confirms that fluctuations in property wealth have a sustained impact on consumer behavior, a trend further corroborated by Australian Bureau of Statistics data linking retail spending to housing market performance.
Consequently, the current market cooling has triggered complex psychological and economic reactions. A reduction in property transactions directly dampens demand for home furnishings, appliances, and renovation services. Furthermore, construction firms, already burdened by elevated material costs, face diminished financial viability if end-sale prices fail to meet expectations, threatening to stall future housing supply. From a psychological standpoint, homeowners exhibit acute sensitivity to price corrections. Even though current values remain historically high, any downward adjustment is often perceived as a financial setback—a phenomenon sometimes termed the "tyranny of the status quo." This ingrained expectation of perpetual capital growth complicates the landscape, maintaining a psychological barrier that indirectly affects new entrants to the market.
Regulatory Overhauls: Tax Reforms and Enhanced Transparency
Beyond natural market forces, a sweeping array of regulatory policies is fundamentally reshaping Australian real estate. Starting this July, rigorous new purchasing regulations have taken effect, mandating comprehensive identity and funding source verifications for both buyers and sellers. Real estate agents, conveyancers, and legal professionals are now legally obligated to report any suspicious transactional behavior directly to AUSTRAC. These stringent measures are designed to combat the billions of illicit funds historically funneled into the property sector, addressing long-standing international criticisms regarding market transparency. By curtailing artificial, illicit demand, these reforms are expected to help clean the market and reduce upward price pressures, theoretically improving the competitive landscape for legitimate buyers.
Simultaneously, the government has announced significant tax reforms targeting property investors, officially unveiled in the May 2026 Federal Budget. The controversial Negative Gearing mechanism has been abolished for established properties purchased after Budget night (May 12, 2026), restricting the benefit exclusively to new builds in a strategic bid to stimulate supply. Importantly, investments made prior to this date are comprehensively grandfathered, retaining their existing tax privileges. Furthermore, the Capital Gains Tax (CGT) framework is set to be restructured effective July 1, 2027. This upcoming change will replace the familiar 50% discount with an inflation-adjusted metric and institute a minimum 30% tax threshold on profits. Despite the delayed implementation of the CGT changes and the grandfathering clauses, these sweeping legislative announcements have already fostered immediate hesitation among investors. Early economic models suggest a significant pullback in investor participation, with institutional projections indicating up to a 20% drop in overall market transaction volumes, placing noticeable downward pressure on national home prices.
However, these demand-side interventions clash with severe supply-side constraints. The government’s ambitious target of constructing 1.2 million new homes over five years is currently facing significant hurdles; recent data for early 2026 indicates a sharp decline in housing starts, leaving the nation's construction pipeline short by roughly 260,000 dwellings against its required trajectory. This chronic undersupply serves as a robust floor under property prices, counteracting the cooling effects of tightened regulations and tax reforms.
The First-Home Buyer's Dilemma
While the government maintains that these regulatory adjustments will effectively cool the market and assist first-home buyers, this demographic continues to face formidable challenges. With the RBA cash rate holding steady at 4.35%—and expected to remain unchanged throughout 2026—the "borrowing ceiling" remains restrictively low. Consequently, while prices may have marginally softened, the actual purchasing power of new buyers has contracted, keeping the dream of homeownership elusive.
Government interventions, such as the expanded 5% deposit guarantee scheme, offer temporary relief but do not address the systemic issue of fundamental affordability. As buyers are increasingly pushed toward outer suburbs, regional areas, or higher-density apartments, even these traditionally affordable options are becoming scarce. Looking forward, if the structural supply deficit is not comprehensively resolved, economic models predict a resurgence of aggressive price growth moving into the 2030s, threatening to permanently price an entire generation out of the housing market.
Looking Ahead: Securing Your Financial Future
Whether you are strategically navigating Australia's evolving real estate market, saving for a future deposit, or managing cross-border investments, securing your financial assets is paramount. As economic landscapes shift, EzyRemit remains steadfast in our commitment to providing robust and compliant financial infrastructure. We are currently in the developmental stages of a new digital ecosystem. While exact features and launch timelines are still being carefully refined, this platform is conceptualized to potentially offer a seamlessly integrated digital financial experience tailored to the modern global citizen. Recognizing the industry’s heightened focus on data protection, our ongoing research includes evaluating various advanced security concepts—potentially exploring next-generation multi-modal biometric frameworks—to further safeguard user information. In the meantime, we invite you to explore our highly reliable global money transfer solutions to experience our ongoing commitment to secure and compliant international transactions.
Disclaimer: The information provided in this article is for general informational purposes only and does not constitute financial, investment, real estate, or legal advice. Regulatory frameworks, tax laws, and market conditions are subject to change.